Credit Score Soundcheck for Smoother Auto Financing
January 06 2026 - JasonMonaghan
The board you’re mixing on
Auto lenders still ride with FICO. Five channels: payment history (35%), utilization (30%), age (15%), new credit (10%), mix (10%). If you only have time to tune two, it’s payments and utilization every time. Payments. A single 30-day late splatters a pretty file. Auto-Pay the minimums. Pay extra before statements. Utilization. Statement balances are the number on the meter. Keep them under 10% of limits if you can. Under 30% still helps. Pay before the cut date. Age. Keep the first card open. New credit. Group auto inquiries inside a short window so the algorithm reads them as one. Mix. Cards plus one installment line get the job done.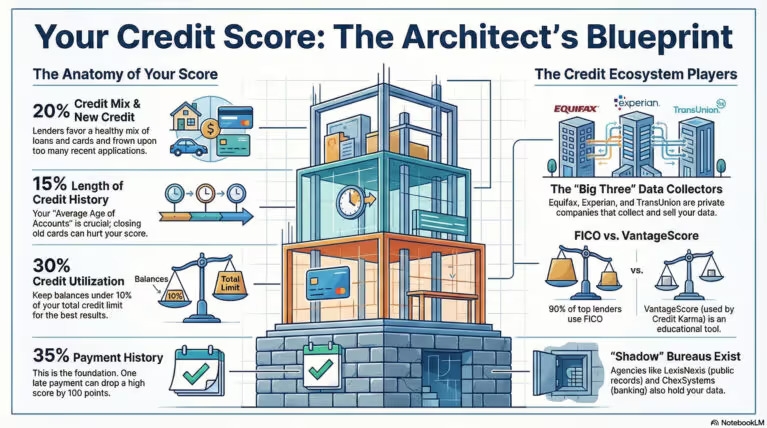
Who tracks vs. who scores
Equifax/Experian/TransUnion maintain your data. FICO converts it to the number the desk quotes. Your app might show VantageScore; it’s fine for trends and different for underwriting.A two-day soundcheck
Stage kit. License, Social Security card, proof of address. PDF them into a folder labeledCredit_Manchester. Pull full reports. AnnualCreditReport.com for all three. Save with dates. Line check.
- Names and Coffee County addresses correct?
- Limits and balances showing right? Any card missing a limit?
- Negatives that aren’t yours, or medical collections coded wrong?
- Any inquiries you don’t recognize?
- Pay before statement cuts.
- Ask for line increases on veteran cards if the bank won’t hard-pull.
- Push heavy spend to debit for a month.
Keep the vintage gear
That oldest card? Keep it active with a tiny subscription and Auto-Pay. If a fee won’t downgrade, weigh the cost before closing.The backstage files
- LexisNexis/SageStream for identity/public records.
- ChexSystems for banking history.
- Innovis for another freeze handle.